
View
Investment Updates


Capital is at risk. The value and income from investments can go down as well as up and are not guaranteed. An investor may get back significantly less than they invest. Past performance is not a reliable indicator of current or future performance and should not be the sole factor considered when selecting funds.
By selecting intermediary or institutional investor I confirm that I am a financial professional and understand that the information should not be distributed to or relied upon by any other persons. It’s provided for general information purposes only and is not personal advice to anyone to invest in any fund or product. Information taken from trade and other sources is believed to be reliable, although we don’t represent this as accurate or complete and it shouldn’t be relied upon as such.


While market turbulence is never pleasant, when stocks pull back like this it can remove some of the speculative ‘froth’ in highly valued areas of the stock market. This can create interesting opportunities for investment teams taking a long-term view.
For us, the first step is always to understand clearly what is happening and why. This is exactly what we as a team discussed last night and this morning.
When President Donald Trump conceded the Republicans’ unexpectedly heavy defeat in the US midterms without disputing its legitimacy, this was met with an initial ‘relief rally’ in equities (company shares).
However, investors quickly turned their attention to concerns that the Democrats will slow the development of US data centres – and this triggered the sell-off in technology companies that spread to wider markets.
Data centres are huge facilities, providing essential infrastructure underpinning the rapid growth of artificial intelligence (AI). But the centres’ size and consumption of energy and water have made them controversial.
New Democrat governors-elect like Gina Hinojosa in Texas have pledged to introduce new laws to regulate the building of data centres. Crucially though, we believe that while costs may rise and timelines lengthen, new data centres will still be built.
What we have seen yesterday and today is markets doing what they do. Pricing in the risk that something might happen, long before the eventual outcome is known. We see considerably more evidence that the buildout of data centres will evolve over time, rather than suddenly stopping.
Technology has been an important driver of markets, productivity and economic growth for decades. We do not believe this has changed because of one election result or one difficult week for semiconductor shares.
The role of the US as a technology leader is one of the reasons why, as investors, we are positive on the country. It is one of the world’s strongest economies, with many leading global companies. The US is also home to world-class research and universities, abundant natural resources and energy, and it has an impressive track record of turning innovation into successful businesses.
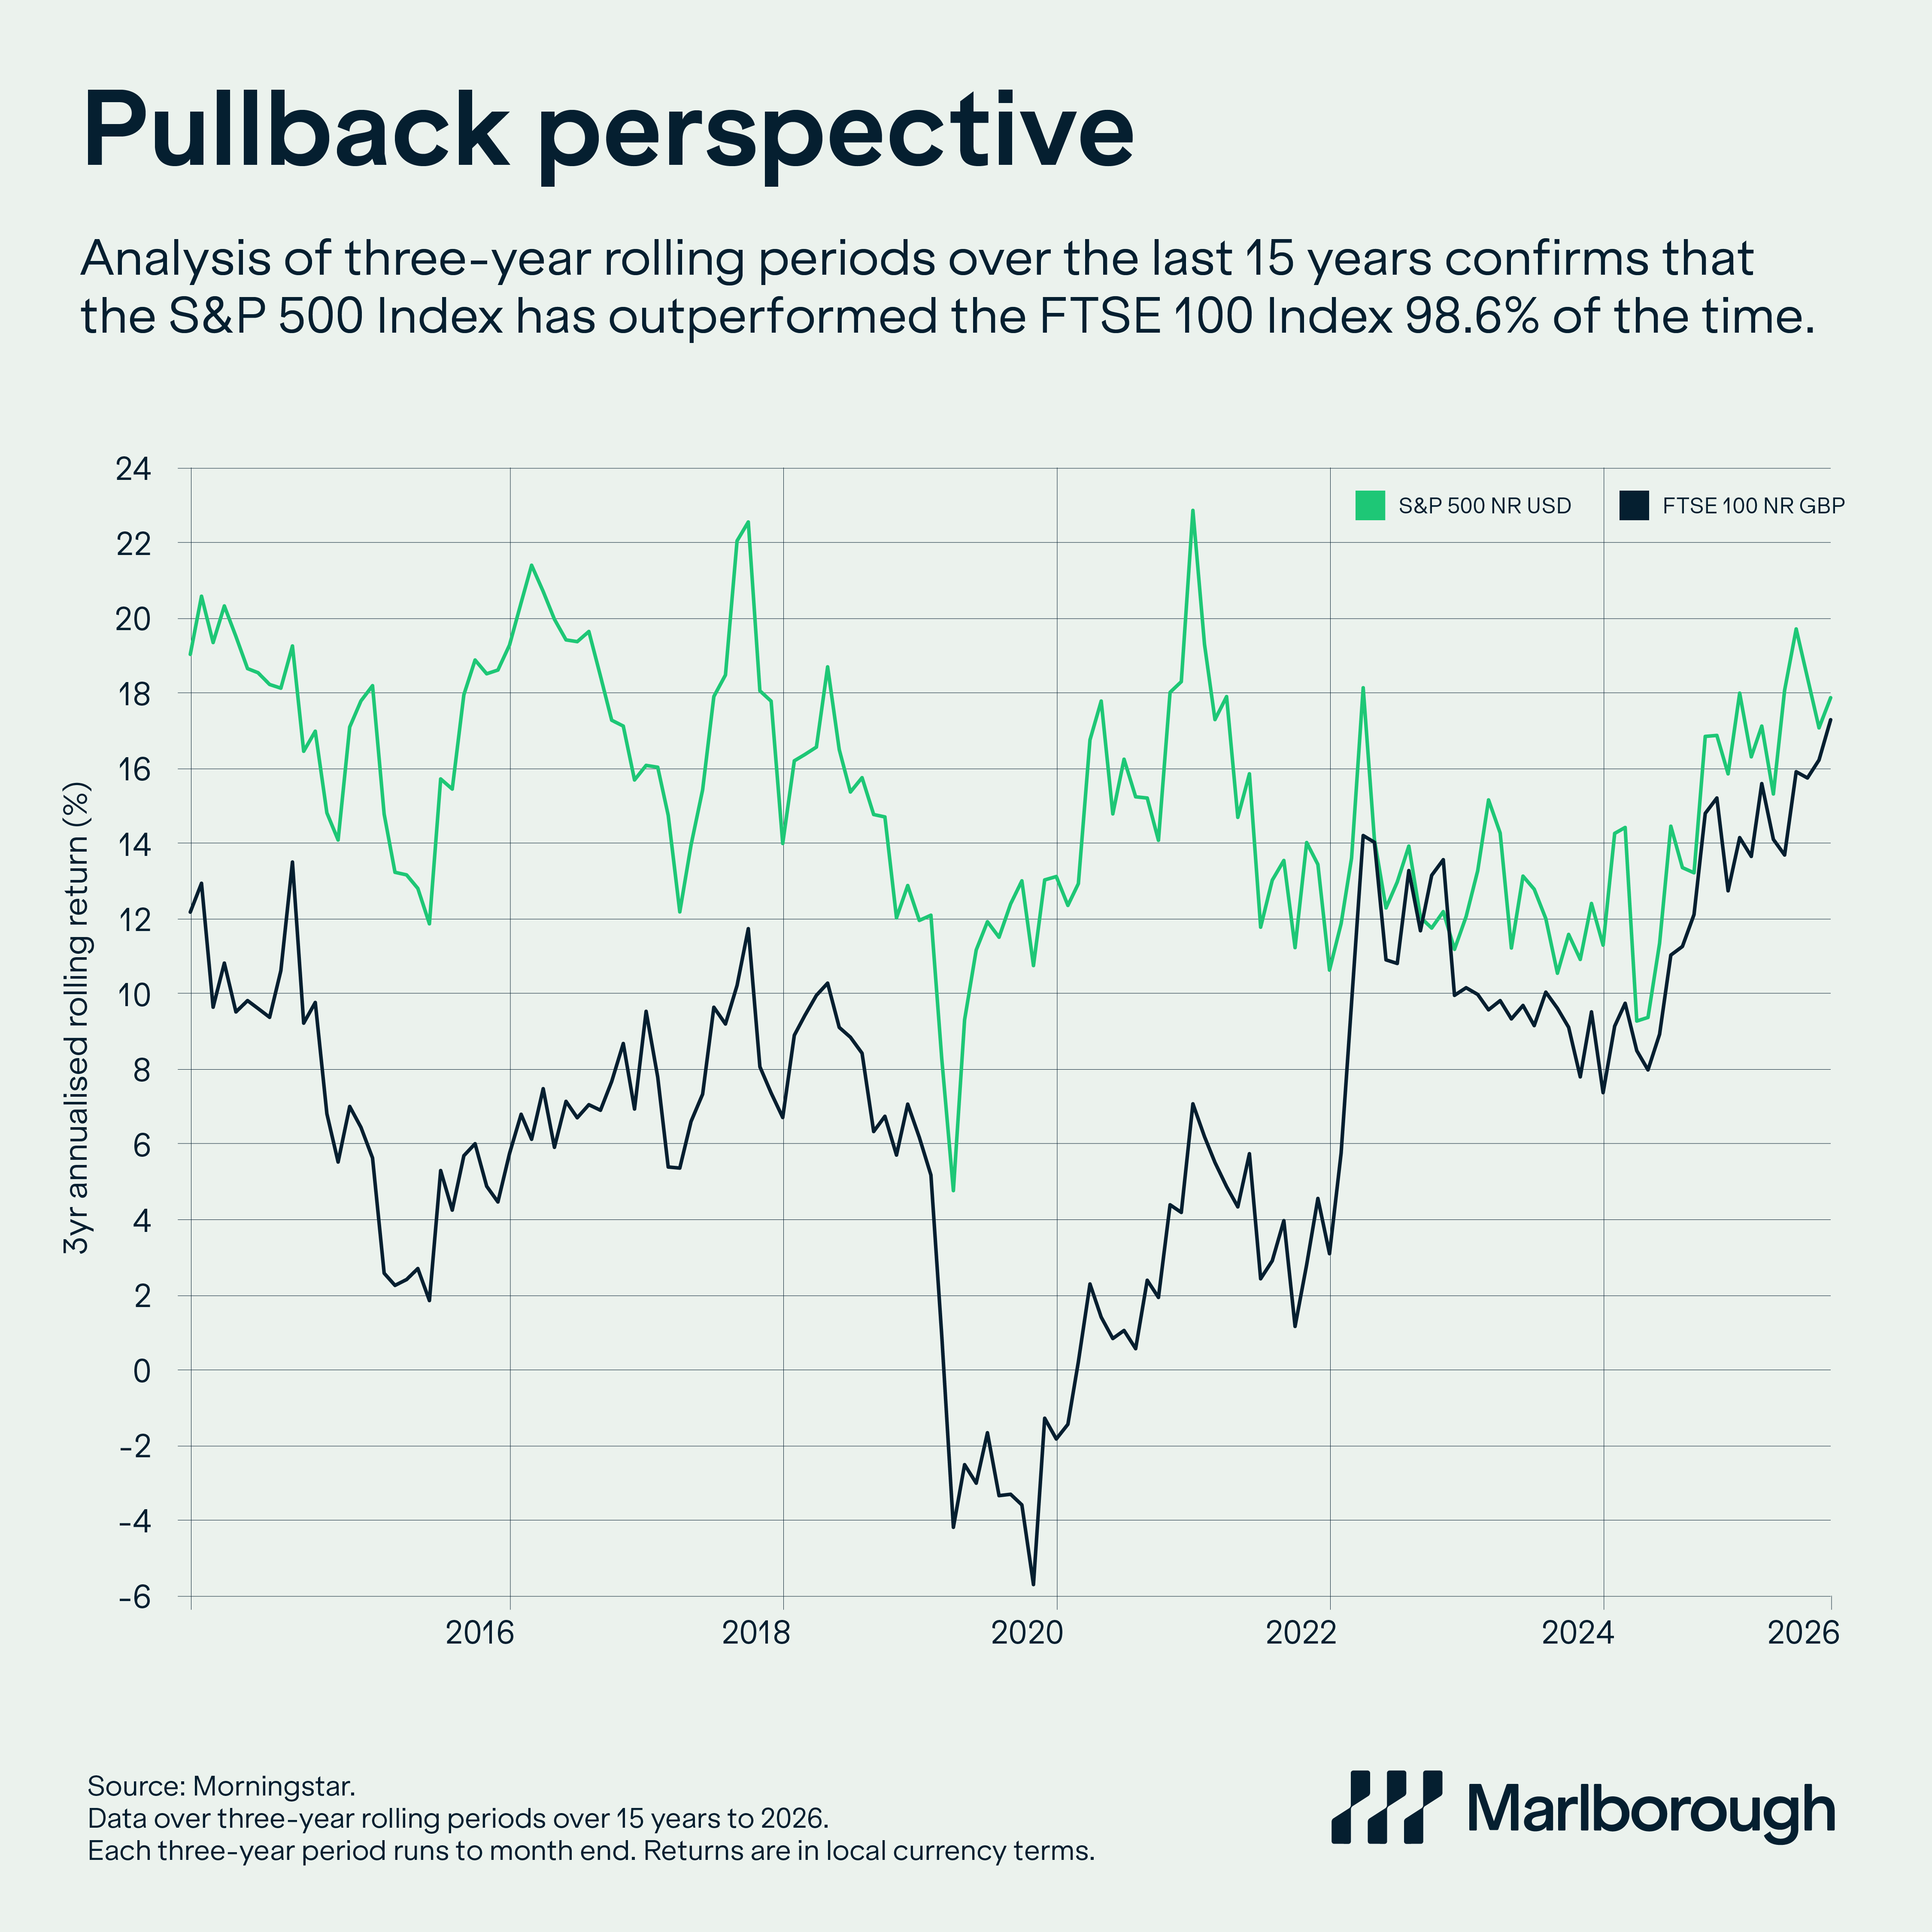
That is why the US remains the largest equity allocation in our portfolios, which are globally focused. There will be times when the UK market – with its high representation of energy companies and low exposure to the technology sector – outperforms. But the data shows that historically the US equity market has consistently outperformed the UK market.
Our chart shows how over three-year rolling periods during the last 15 years the S&P 500 Index has outperformed the FTSE 100 Index 98.6% of the time.
As well as being data-driven and disciplined, we are dynamic in the way we manage clients’ investments. Our portfolios are not positioned on the assumption that recent winners will simply continue to outperform. This is one of the reasons we have been adding to the UK equity allocation in our portfolios recently, and we trimmed our exposure to Japan and emerging markets.
We are also strong believers in the importance of diversification across asset classes, and we have been adding to our allocation to government bonds*, which we believe offer an attractive opportunity with yields** at current levels. We have increased the active*** component of our government bond allocation through IFSL Arbion Sovereign Opportunities.
Markets are doing what markets often do: repricing a new risk before anybody knows precisely how large that risk will ultimately prove to be.
The political environment for US data-centre development has changed, and that deserves our attention. But greater political scrutiny is not the same thing as the end of the AI investment cycle, just as a sharp fall in semiconductor shares does not in itself undermine a long-term structural growth trend.
Just as markets are doing what they do, we, as an investment team, will carry on doing what we do on our clients’ behalf. We will continue to apply our long-term data-driven approach, remaining vigilant as we assess risks and standing ready to act dynamically to seize on opportunities.
*Bonds are interest-paying financial products issued by governments, companies and other institutions when they want to borrow money from investors.
**Yield is the annual income a bond or other investment pays, expressed as a percentage of its current market price.
***When a fund is actively managed, the fund manager decides which investments to buy and sell and when, with the aim of outperforming the overall market.
This article is provided for general information purposes only and should not be construed as personal financial advice to invest in any fund or product. These are the investment manager’s views at the time of writing and should not be construed as investment advice. The opinions expressed are correct at time of writing and may be subject to change. Capital is at risk. The value and income from investments can go down as well as up and are not guaranteed. An investor may get back significantly less than they invest. Past performance is not a reliable indicator of current or future performance and should not be the sole factor considered when selecting funds.

